✅ Today’s Checklist:
- A financial counselor on what your 401(k) is actually doing
- Thania’s tips for creating a fall home gym
- Recipe of the week: Cabbage Roll Skillet
🗓️ NEXT THURS 9/24 @ 9AM PT: 42% of you told us your company handed you AI with zero instructions. 3 AI Plays is the training you should have gotten. Free, one hour. Save your seat.
🤔 Trivia: What anatomical feature do humans have that no other animal does? Find out.
QUICK LINKS
🔥 Menopause care is opening up as Planned Parenthood steps in across five states.
🔬 GLP-1s may curb addiction risk too, per a 600,000-veteran study.
🥗 Chewing raw spinach at breakfast won’t reset your sweet tooth, sorry.
🔍 An exercise scientist’s take on peptides, NAD, and the creatine hype.
FITNESS
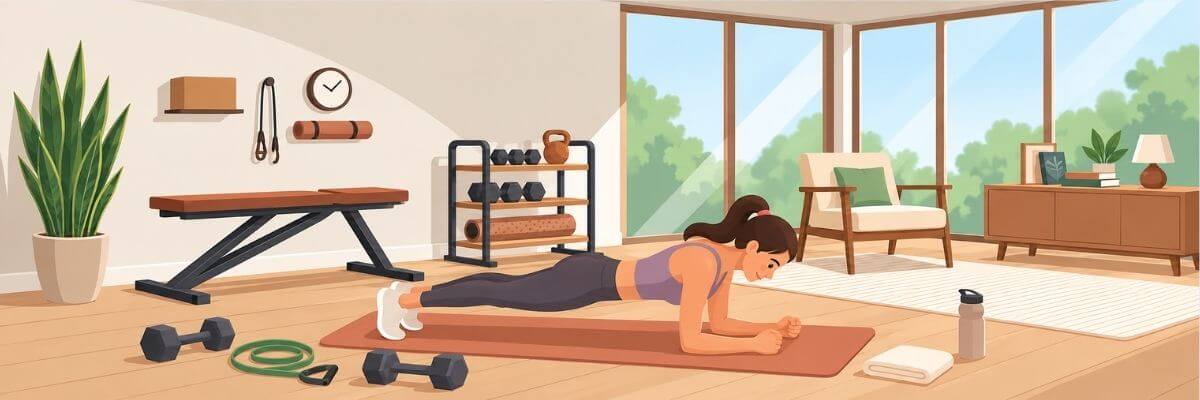
The Home Gym That Kills the Excuse to Skip
Something about fall has always felt like a fresh start to me. New school year, new notebooks, that clean-slate energy where you get to reset and try again. So before the holidays swallow the next three months whole, this is the moment to point that energy at your health, so you walk into the new year with a foundation already built instead of a resolution you’re starting from scratch.
One thing up front, because this topic gets weird fast: this is not a skinny-ozempic agenda. I already wrote the piece about being done chasing the ideal body. This is about having somewhere to move your body that you will actually use.
Here’s why I went the home route. I always struggled to actually get myself to the gym. A setup at home killed the excuses. It also killed the embarrassment, the not knowing how to work a machine, the needing to stop and catch my breath in the middle of a class while everyone else keeps going. At home, the whole thing is mine. My pace, my plan, my rules.
So here’s how to build a setup that makes showing up the easy choice.
Start with one anchor machine
One solid piece that does a lot beats a garage full of equipment. FitTransformer is a modular home gym built around a single core that becomes a whole rack of machines, so you get strength, rowing, and cardio without filling a room. If you’d rather buy commercial-grade gear that lasts forever, Matrix Fitness is the premium end. To compare a full lineup in one place before you commit, Johnson Fitness and Wellness carries strength and cardio across a range of brands.
If that all feels like too much, start with a dumbbell set. I like this cute pink one for a living room, and for my Airbnb home gym I used this set that goes up to 25 lbs.
Add cardio you’ll actually use
Cardio is where consistency lives, so pick the one you’ll look forward to. A smart spin bike like Yesoul brings the studio-cycling feeling home, screen and all. Schwinn is the trusted classic for bikes and ellipticals if you want proven and no-fuss. If you’re tight on space or want to move more during the workday, a Wellfit walking pad slides under a standing desk so you can rack up steps while you answer emails.
Get a program so you’re not guessing
Owning the gear is half of it. The other half is knowing what to do with it, which is where most people stall out. A guided program means you never stand there wondering what today is supposed to be. Something like Sweat by Kayla Itsines or Bodi hands you the plan, presses play, and lets you follow along.
Back it up with nutrition support
Training is only part of the picture, and food is where most of us actually get stuck. An app like Noom helps you understand how you’re eating and build habits that stick, without turning every meal into a math problem.
Bring in the professionals when you need them
Some goals are worth a pro. A nutritionist can tailor the food side to your real life. And yes, if it’s right for you, a GLP provider.
I’m a big proponent of GLPs when your body has a predisposition to things like metabolic syndrome, PCOS, obesity, or diabetes. The science on how these medications actually work is a lot less dramatic than the internet makes it sound. Some people genuinely follow a balanced diet and a solid training program and still don’t get the results they’ve earned, because of how their body is wired. If that’s you, grinding three times as hard as everyone else is exhausting, and nobody hands out medals for it.
Talk to a provider you trust, and if it’s the right call for your body, take the damn GLP. Your body, your choice. Do what’s good for you!
Forget the fancy studio and the January 1st countdown. All you need is a corner of a room, a couple of good pieces, and the decision to begin now, while everyone else is waiting for the ball to drop. Give yourself the fresh start. Fall’s the perfect time to take it.

Thania (TA Content Mgr)
THE MARKUP
Why the Same Shot Costs $59 or $500
Someone in your group chat is paying $500 a month for a GLP-1. Someone else is paying $59 for the same doctor-prescribed compounded medication out of a US-licensed pharmacy.
The ingredients in compounded GLP-1s cost around $5 to produce. So those hundreds more you’re paying? That’s the markup, not the medication.
Collective pools members’ buying power to negotiate GLP-1 pricing straight from US pharmacies, the same model Thrive Market used on organic groceries. $199 annual membership (less than $17/month) gets you compounded semaglutide at $59/month or tirzepatide at $69/month, and the price stays the same at any dose.
You also get unlimited messaging with a real doctor, dose adjustments when needed, plus nutrition support most programs skip. Try it 21 days free, (only pay for your medication) and see why better care doesn’t have to cost more.
FEE CHECK
The 1% Fee That Costs You $64,000
Long before I became an Accredited Financial Counselor®, I got my first 401(k) and had no idea what it was or how it worked. I picked the default options during onboarding and moved on. Years later, when I finally looked, I was embarrassed: thousands of dollars of my own money, and I couldn’t tell you what it was doing. Plenty of people are in exactly that spot. A 2024 survey by Beyond Finance found 43% of Americans don’t know what a 401(k) really is.
The reframe that changed how I treat mine: a 401(k) is an investing account, and used well, it is the most underrated passive income stream you will ever have.
The basics, quickly
You contribute, your employer may match part of it, and that money gets invested, usually in a mix of stocks and bonds. Contribution limits go up most years, so check the IRS site for current numbers.
If your employer offers a match, contribute at least enough to get all of it, even if you have debt. Your match is part of your compensation. Turning it down is accepting a lower salary.
Two mistakes I see constantly: never bumping up your contribution as your income grows (even 1% more can mean thousands down the road), and not knowing you have a choice between Traditional (tax break now, taxed later) and Roth (taxed now, tax-free withdrawals later). Neither is universally better. The mistake is not knowing the option exists.
Know your vesting schedule, too. Your own contributions are always 100% yours. Your employer’s match might not be, and leaving a job too soon can forfeit money you thought was already yours.
Fees matter more than you think
Without looking, do you know what your money is invested in? Most people check out here. Your 401(k) usually gives you two routes: a target date fund that manages your stock and bond mix automatically, or your own low-cost index fund portfolio. Both can work. Every fund carries a fee called an expense ratio, and a fraction of a percent compounds into real money.
The Department of Labor ran the numbers on a $25,000 balance, 35 years to retirement, and a 7% average annual return:
-
Paying 0.5% in fees → about $227,000 at retirement
-
Paying 1.5% in fees → about $163,000
One percentage point costs $64,000, or 28% of the final balance. You are almost certainly paying fees right now, and you can find out exactly what they are.
The risk most people miss
Most people worry about downturns and invest more conservatively than they should. For most of your career, with decades until retirement, investing more aggressively (more stocks, fewer bonds) can get you to a more comfortable retirement, because you have time to weather the drops.
That changes within 5 to 10 years of retirement, when it is worth managing “sequence of returns risk.” It sounds more intimidating than it is: the same average return lands differently depending on when the good and bad years happen. A 20% drop at 35 barely matters, since your money has decades to recover. That same drop the year you retire is a different story, because you are withdrawing while your account is down and locking in losses.
Two people can have identical average returns and end up in very different places. Managing this risk means being invested in a way that protects you in a downturn.
What to do right now, no matter your age
Log into your 401(k) today:
- Check your match. Are you contributing enough to get all of it? Could you contribute beyond it?
- Look at what you are actually invested in. How much is in stocks? How much is in bonds?
- Check your expense ratio. One percentage point can cost you tens of thousands over a career.
A 401(k) is one of the simplest tools you have to build real wealth and freedom. Treat it like one.
— Tess Waresmith (Accredited Financial Counselor®)
P.S. I still remember how silly I felt the day I finally understood my own 401(k) after years of confusion. If that’s you right now, you’re in good company. Come hang out here.
LOW LIBIDO FIX
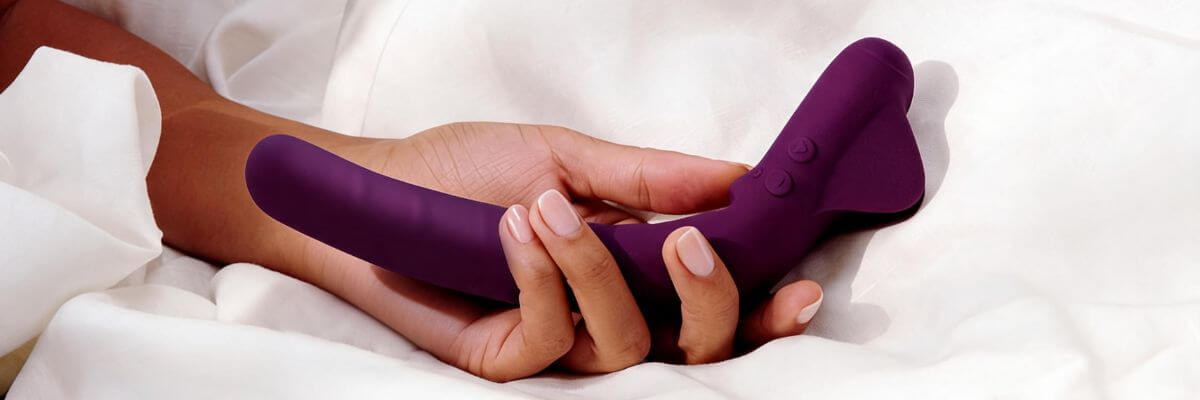
The Toy Your Gynecologist Would Actually Sign Off On
Most of us have bought one of these off a listicle and a hopeful guess. This one comes with data.
Crescendo 2 was designed with urologists and OB-GYNs as an FDA Class II device, and independent studies published in the Journal of Sexual Medicine found it increased arousal by up to 73% and natural lubrication by up to 93%. That matters if you’re in perimenopause, on an antidepressant, or just tired of white-knuckling through dryness nobody warned you about.
It bends, so it sits where you actually want it. Six motors, sixteen intensity levels, customizable patterns, and an app if you want a partner in on it.
It’s also FSA/HSA eligible, which is the part nobody expects. Good use of funds you have to spend down this year anyway.
STAFF PICKS
Stuff We’re Loving This Week
👉 Wake up to what matters. Life_ turns Gmail and Google Calendar into one calm morning brief.
🧴 MERIT’s Rich Moisturizer fixes tight, dull skin, and you can get it now, months before it launches in January.
👗 Skip the bra, keep the confidence with Grippy Cakes, perfect for outfits that refuse to cooperate with straps.
🪥 Flossing gets a lot less annoying with quip’s cordless water flosser.
JUST FOR FUN
COMMUNITY
 Upcoming Events
- TODAY 9/16 @ 11:30AM PT: Coworking Session (SGS Only* | Join the waitlist)
- Thu 9/17 @ 10AM PT: Beyond the Brand with Laura Weldy (SGS Only* | Join the waitlist)
- Fri 9/18 @ 9AM PT: Part 2 of a 2-Part Investing Series with Tess Waresmith (SGS Only* | Join the waitlist)
- Thu 9/24 @ 9AM PT: 3 AI Plays to Get Your Hours Back and Credit for the Work You Do
- Wed 9/30 @ 3PM PT: Gossip Hour: What Happens Here, Stays Here (SGS Only* | Join the waitlist)
* Smart Girl Society is our private community for women who want deeper conversations, accountability, and tools that actually make life easier. Join the waitlist to get in the next round.
👩🍳 Recipe of the Week: Cabbage Roll Skillet (thanks to TA reader, Nicole, for sharing!).
😋 Have a recipe you love? Share it here.

SPILL THE TEA
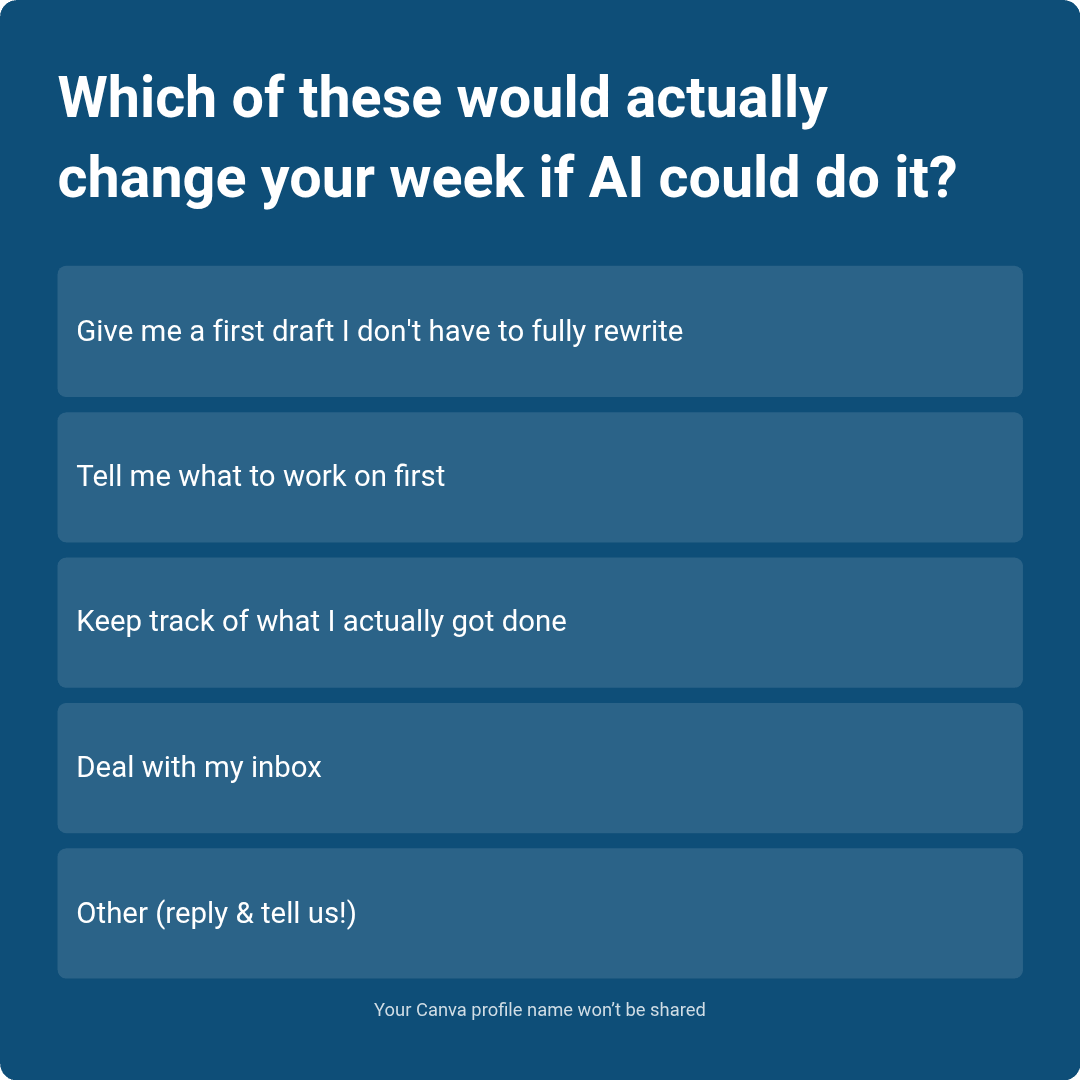
Take Our Poll
Have more feedback? 💌 Reply to this email and tell us.
✨ P.S. Want more inspiration and positivity to kick off your week? Sign up for our Motivational Monday texts (U.S. only).
👀 Want to see if your company is a good fit for our 250k+ ambitious readers? Join our Sponsor Waitlist here.